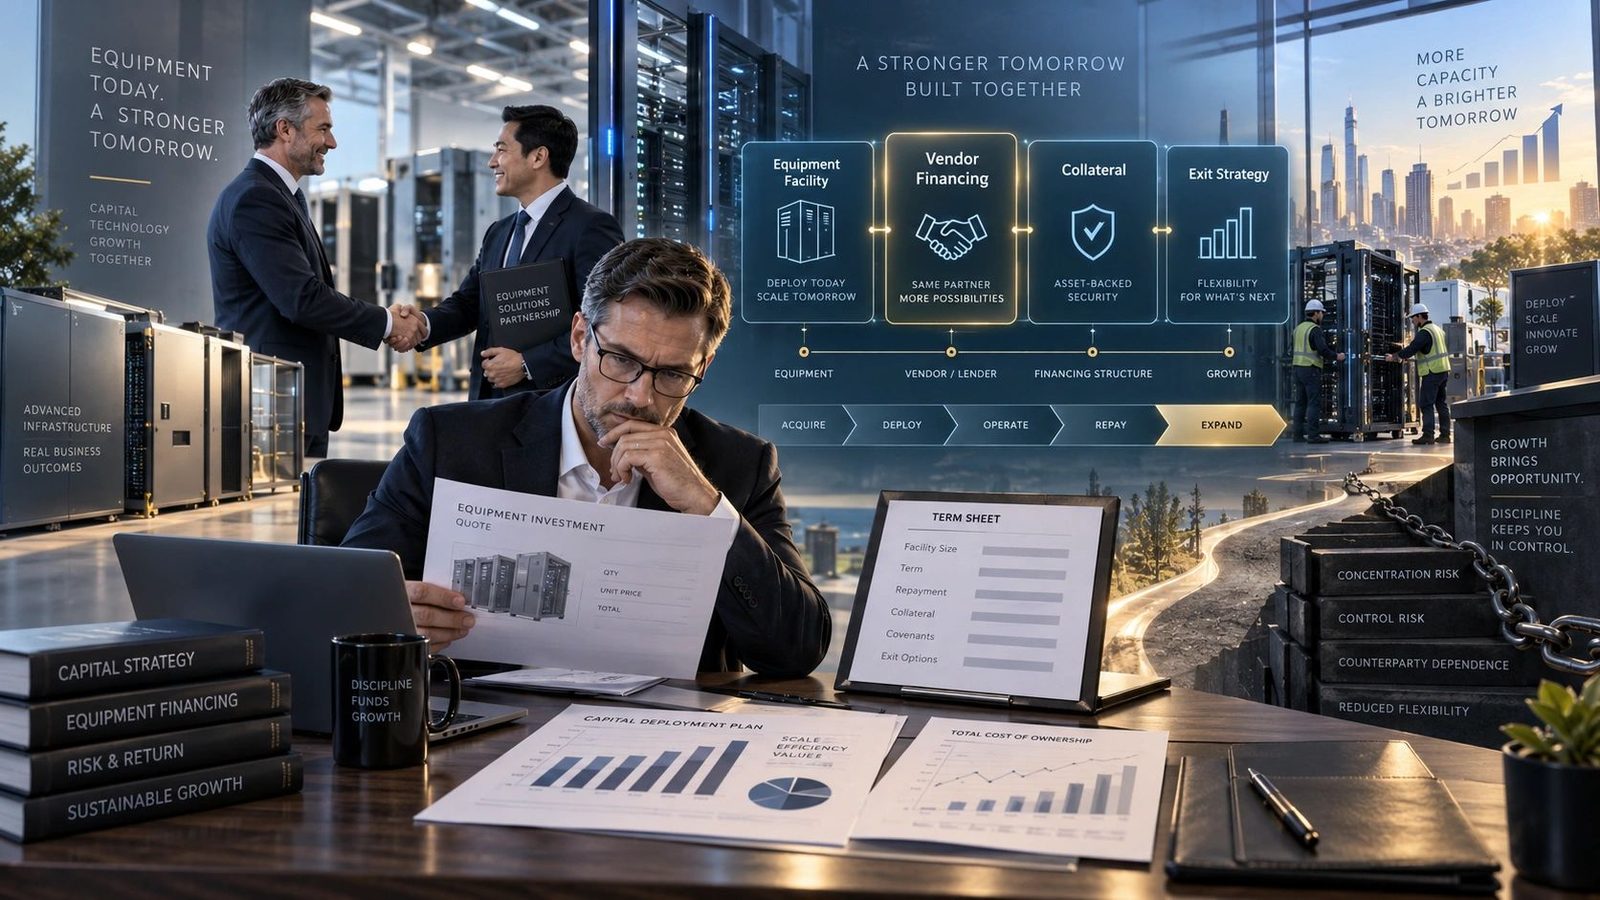
Vendor financing can solve two problems at once: a business obtains the equipment or capacity it needs, and the supplier helps fund the purchase. When the asset is specialized, expensive or difficult for a traditional lender to value, that alignment can unlock a transaction that would otherwise move slowly—or not move at all.
The convenience is real. So is the concentration.
On October 1, 2026, Reuters reported that Broadcom agreed to lend Anthropic up to $42 billion for infrastructure spending tied to compute capacity and chip-related arrangements. Broadcom is not simply a vendor in this structure. It is also a financing source, a strategic technology partner and a company that expects Anthropic to become a major customer. The arrangement illustrates a broader capital-markets shift: suppliers with strong balance sheets are using financing to support customer investment and secure long-term demand.
For executives, commercial real estate sponsors, family offices and capital partners, the lesson is not that vendor financing is inherently risky. It is that a transaction becomes more complex when the same party influences the asset, the price, the financing and the customer’s ability to keep operating.
The right question is not only, “How much capital is available?” It is, “What happens to the business if the vendor relationship changes before the financing is repaid?”
What changed in strategic equipment finance
Reuters reported on October 1 that Broadcom has agreed to lend Anthropic up to $42 billion to finance infrastructure spending. According to the report, the financing could cover roughly one-third of Anthropic’s $125.2 billion commitment for a five-year lease of tensor processing unit computing capacity. The debt instruments may be convertible into Anthropic shares, and Broadcom may designate a financing partner.
The commercial relationship is equally important. Anthropic is expected to become Broadcom’s largest compute customer in 2027, while Broadcom’s technology is central to the infrastructure Anthropic expects to use. An April 2026 Broadcom filing described an expanded collaboration under which Anthropic would access approximately 3.5 gigawatts of next-generation TPU-based capacity through Broadcom beginning in 2027. Anthropic separately described the expansion as part of its effort to build capacity for customer growth in its April partnership announcement.
This is more than a large loan. It connects four economic relationships:
- The supplier provides or helps arrange critical technology.
- The customer commits to large future capacity.
- The supplier or its financing partner provides debt.
- The debt may create an equity interest through conversion.
That combination can align the parties around growth. It can also make a disagreement over pricing, performance, capacity or repayment affect several parts of the business at the same time.
Reuters reported that Anthropic disclosed potential conflicts arising from Broadcom’s roles as hardware supplier and financing partner. The company also warned that certain payment or performance defaults could accelerate a substantial portion of its lease obligations while limiting access to the $42 billion facility. Anthropic had deposited cash into a restricted account for Broadcom’s benefit and could be required to add more under certain circumstances.
Those details are the heart of the financing issue. A large commitment is not the same as unrestricted liquidity. Availability conditions, restricted cash, cross-defaults and accelerated obligations determine how much financial flexibility the facility actually provides.
Why vendors can finance assets that banks approach cautiously
A specialized vendor may understand the equipment better than a general commercial lender. It may know production costs, replacement demand, maintenance requirements, software dependencies and resale channels. That knowledge can help it underwrite collateral that outsiders view as difficult to value.
The Equipment Leasing and Finance Association notes that manufacturer and vendor financing can help customers acquire equipment while supporting the manufacturer’s sales and customer relationships. A manufacturer may also be better positioned to remarket used equipment or take residual-value risk. These capabilities can reduce monthly payments or support a structure that a conventional lender would not offer. ELFA’s vendor-finance overview explains these commercial advantages.
But expertise does not eliminate risk. It changes who is best positioned to understand and absorb it.
The Office of the Comptroller of the Currency emphasizes that equipment lessors should test asset values over time, monitor residual exposure and avoid relying on unreasonable residual assumptions. Its Lease Financing handbook highlights the importance of asset valuation, residual-realization history and concentration by asset class, manufacturer and term.
This matters most when the equipment changes quickly. Reuters reported on October 1 that lenders evaluating AI-chip financing were seeking stronger guarantees because of uncertainty about useful life and residual value. The report said banks typically depreciate chips over three to four years, while Nvidia has argued for a much longer economic life. That disagreement is not merely accounting. It directly affects advance rates, amortization, guarantees, pricing and refinancing risk.
The same principle applies outside technology. Medical devices, manufacturing lines, vehicles, restaurant equipment, energy systems and construction machinery can all lose value faster than their financing amortizes. A vendor’s willingness to lend may help the purchase close, but the borrower still needs a repayment schedule that matches the asset’s productive life.
The five risks hidden inside an attractive vendor facility
Counterparty concentration
If one party provides the equipment, maintenance, software, capacity and capital, the borrower may have limited alternatives when something goes wrong. A pricing dispute can become an operating disruption. A service failure can become a covenant problem. A refinancing request can become leverage in a commercial negotiation.
Borrowers should measure concentration across the entire relationship, not only the debt balance. The relevant exposure includes replacement cost, switching time, data migration, spare parts, technical support and revenue that depends on the vendor’s platform.
Asset obsolescence
The financing term may exceed the equipment’s useful economic life. If the asset becomes inefficient or unsupported before the debt matures, the borrower could be paying for capacity that no longer produces competitive revenue.
Amortization should reflect the shorter of the expected useful life, contract life and dependable revenue period. A balloon payment based on optimistic resale value may look inexpensive today but create a refinancing problem later.
Cross-default and acceleration
Vendor arrangements often involve several contracts: purchase orders, equipment leases, service agreements, licenses, supply commitments and loans. A default under one agreement may trigger remedies under another.
Executives should map every cross-default, termination right and acceleration clause. They should know whether a service dispute can suspend financing, whether a financing default can terminate equipment access, and how much becomes immediately due after a breach.
Restricted liquidity
A headline facility may include delayed draws, milestones, borrowing conditions, cash-collateral requirements or vendor approval rights. Funds may be available only for specified purchases rather than general working capital.
That distinction matters. A business can have a large committed facility and still lack cash for payroll, inventory, integration costs or a temporary revenue shortfall. Restricted accounts should be included in liquidity reporting but excluded from unrestricted operating cash.
Conflicted incentives
A vendor wants to sell equipment and protect its financing. A borrower wants reliable capacity, competitive pricing and flexibility. A financing partner wants predictable repayment and enforceable collateral. Those goals may overlap, but they are not identical.
The structure should therefore separate commercial acceptance from credit approval. Equipment performance, financing availability and strategic forecasts should each receive independent review. No party should rely solely on the vendor’s sales case to support debt repayment.
A practical capital structure for vendor financed equipment
The cleanest vendor-finance structures allocate each risk to the party best able to manage it.
Consider an illustrative $20 million equipment deployment. The vendor finances $16 million, and the buyer contributes $4 million. If the $16 million obligation amortizes evenly over five years, approximately $9.6 million of principal would remain after two years, before considering interest or fees. If the equipment’s realizable value at that point is only $8 million, the debt would exceed the collateral value by $1.6 million.
That gap does not automatically make the financing unsound. The primary repayment source may be operating cash flow rather than liquidation. But it shows why collateral value, cash flow and amortization must be evaluated separately.
A more resilient structure might include:
- A senior equipment loan sized to conservative collateral value.
- Borrower equity or subordinated capital that absorbs early depreciation.
- Milestone-based draws tied to delivery, installation, testing and revenue readiness.
- Maintenance and performance obligations that survive assignment of the financing.
- A working-capital line from a separate lender for payroll, inventory and receivables.
- Cash reserves sized to installation delays or slower customer adoption.
- Purchase options, replacement rights or upgrade provisions before obsolescence.
- A takeout plan that does not depend on the vendor remaining willing to refinance.
This layered approach may cost more than a single bundled arrangement. It can also prevent one commercial dispute from controlling every source of liquidity.
What borrowers should negotiate before accepting vendor capital
The strongest time to negotiate flexibility is before the equipment is installed and switching costs become high.
Separate price from financing economics
Compare the equipment price, financing rate, fees, maintenance charges, minimum purchase commitments and residual assumptions against independent alternatives. A low stated rate can be offset by a higher purchase price or inflexible service terms.
Define acceptance and performance standards
Draws should follow verified delivery and acceptance. The documents should state what happens if equipment fails testing, arrives late or cannot achieve contracted performance. The borrower should not fund defective or unusable assets merely because the financing closed.
Limit cross-defaults
Cross-defaults should be material, clearly defined and subject to appropriate cure periods. A minor service disagreement should not accelerate an entire equipment facility. The borrower should know whether obligations are cross-collateralized with unrelated assets or guarantees.
Preserve assignment and servicing continuity
The vendor may sell or syndicate the financing. Borrowers should understand who can become the lender, whether servicing can change, and whether equipment warranties and maintenance obligations remain enforceable after assignment.
Protect replacement and upgrade rights
Rapidly changing equipment may need upgrades before the original debt matures. The documents should address substitutions, trade-ins, early buyouts, transfer costs and treatment of remaining obligations.
Build an independent liquidity source
Vendor financing normally funds the vendor’s product. It may not fund the broader cash conversion cycle. A company installing new equipment may also need inventory, labor, insurance, tenant improvements, customer acquisition and receivables financing.
The capital plan should identify those needs before closing. Otherwise, the business may own more productive capacity but lack the cash to operate it.
Implications for commercial real estate and operating companies
Vendor financing is not limited to machinery. Commercial real estate owners increasingly rely on equipment-heavy systems such as HVAC, building controls, solar installations, battery storage, elevators, data infrastructure and specialized tenant improvements.
These investments can be financed through equipment leases, energy-service arrangements, commercial property financing or project-level capital. The sponsor must determine whether the asset is legally and economically separate from the real estate, whether a lender can remove it, and how the financing interacts with the mortgage.
Three questions deserve early attention:
- Does the mortgage lender permit the equipment lien or lease?
- Will removal damage the property or interrupt tenant operations?
- Does the improvement create enough durable net operating income to service its financing?
Intercreditor agreements and landlord waivers can become closing conditions. Waiting until documentation is advanced to address them can delay the transaction or reduce proceeds.
Operating companies face a different issue: new capacity often creates a working-capital requirement before it creates cash. More production can require more raw materials, labor and receivables. Equipment financing should therefore be paired with a 13-week cash forecast and a longer operating model that shows utilization, gross margin, collection timing and maintenance costs.
Implications for family offices and capital partners
Vendor-backed transactions can appeal to private capital because they combine a strategic sponsor, identifiable assets and long-term customer demand. They may also offer structured downside protection through collateral, guarantees, cash sweeps or conversion rights.
The diligence must go beyond the borrower’s financial statements.
Capital providers should test:
- Whether equipment demand is independent or supported by reciprocal purchasing.
- Whether the asset has a secondary market outside the original customer-vendor relationship.
- Whether revenue contracts are firm, cancellable, concentrated or dependent on the same vendor.
- Whether the financing can be serviced under lower utilization and slower collections.
- Whether the supplier remains obligated to maintain, replace or support the equipment after assigning the debt.
- Whether restricted cash is truly available to lenders and how replenishment affects operating liquidity.
- Whether conversion rights, warrants or other equity features compensate for risk without weakening governance.
- Whether the exit depends on refinancing in a market that may value the asset differently.
Private capital can fill a genuine gap when banks do not have the expertise or appetite for specialized assets. The opportunity is strongest when the transaction produces independently verifiable cash flow—not when financing merely circulates between a vendor and its customer.
The Apex perspective
At Apex Commercial Funding, we view vendor financing as one component of the capital stack, not as a complete capital strategy.
Our starting point is the operating requirement. What equipment or capacity does the business need? How does it generate cash? How quickly can the asset become productive? What happens if installation, customer adoption or collections take longer than expected?
We then separate four decisions:
- Asset economics: price, useful life, maintenance and residual value.
- Credit structure: advance rate, amortization, covenants, guarantees and remedies.
- Operating liquidity: cash required for payroll, inventory, receivables and ramp-up.
- Exit flexibility: refinancing, replacement, purchase, sale and vendor transition.
That separation matters because the most convenient source of capital is not always the best source for every need. A vendor may be well suited to finance equipment. A bank or asset-based lender may be better suited to finance receivables. A family office may provide subordinated or preferred capital for the ramp-up. Real estate debt may support improvements that create durable property cash flow.
The objective is not to eliminate interdependence. Large investments naturally create it. The objective is to understand the dependency, price it and prevent a single relationship from becoming an unplanned control point over the business.
Eight questions to answer before closing
Before accepting vendor financing, decision-makers should be able to answer these questions in writing:
- Who owns the equipment during and after the financing term?
- What operating cash flow—not refinancing—repays the obligation?
- Does amortization match the asset’s conservative useful life?
- Which commercial defaults can stop financing or accelerate payment?
- How much unrestricted liquidity remains after deposits and reserves?
- Can the lender assign the debt without preserving vendor obligations?
- What replacement, upgrade and early-exit rights does the borrower have?
- Which independent capital source supports working capital and contingencies?
If those answers are clear, vendor financing can be a powerful growth tool. If they are not, a large facility can conceal a smaller amount of real flexibility than the headline suggests.
Build the capital plan before dependence becomes leverage
Vendor financing works best when the borrower negotiates from a position of choice. That means comparing structures early, identifying operating liquidity separately and resolving lien, assignment and cross-default issues before installation begins.
Apex Commercial Funding helps business owners, commercial real estate sponsors, family offices and capital partners evaluate equipment finance, asset-based lending, private credit, working-capital facilities and layered capital structures. If a strategic vendor is offering to finance your next expansion, we can help test the economics, identify the hidden dependencies and build a capital plan around the business—not only the asset.
Contact James Fillmore II at 240-535-9291 or James@apexcommercialfunding.com to discuss your financing objectives.
This article is for general informational purposes only. It is not a commitment to lend, an offer to sell securities, or legal, tax, accounting or investment advice. Financing availability and terms depend on underwriting, documentation, collateral, market conditions and applicable law.
Hashtags: #VendorFinancing #EquipmentFinance #CommercialFinance #PrivateCredit #WorkingCapital #CapitalStrategy #AssetBasedLending #FamilyOffice #ApexCommercialFunding